
Discus Fish of Cobo and Samuel Tse of Animoca Brands discuss how AI agents, digital identity and blockchain could change the way money moves.
Updated
November 2, 2026 12:03 PM
The Agentic Economy Summit at CVCF 2026 explores how AI agents and digital assets could shape the future of business and finance. IMAGE: CYBERPORT
For an AI agent to manage money on someone’s behalf, it needs more than the ability to follow instructions. It must be able to establish whom it represents, access funds and transact within agreed limits.
These are among the questions informing the discussion of AI and digital assets at Cyberport Venture Capital Forum (CVCF) 2026. Ahead of the forum, Discus Fish, CEO and Co-founder of Cobo, and Samuel Tse, Head of Investment and Corporate Finance at Animoca Brands, shared their views on how this convergence could develop—and where they see opportunities for businesses.
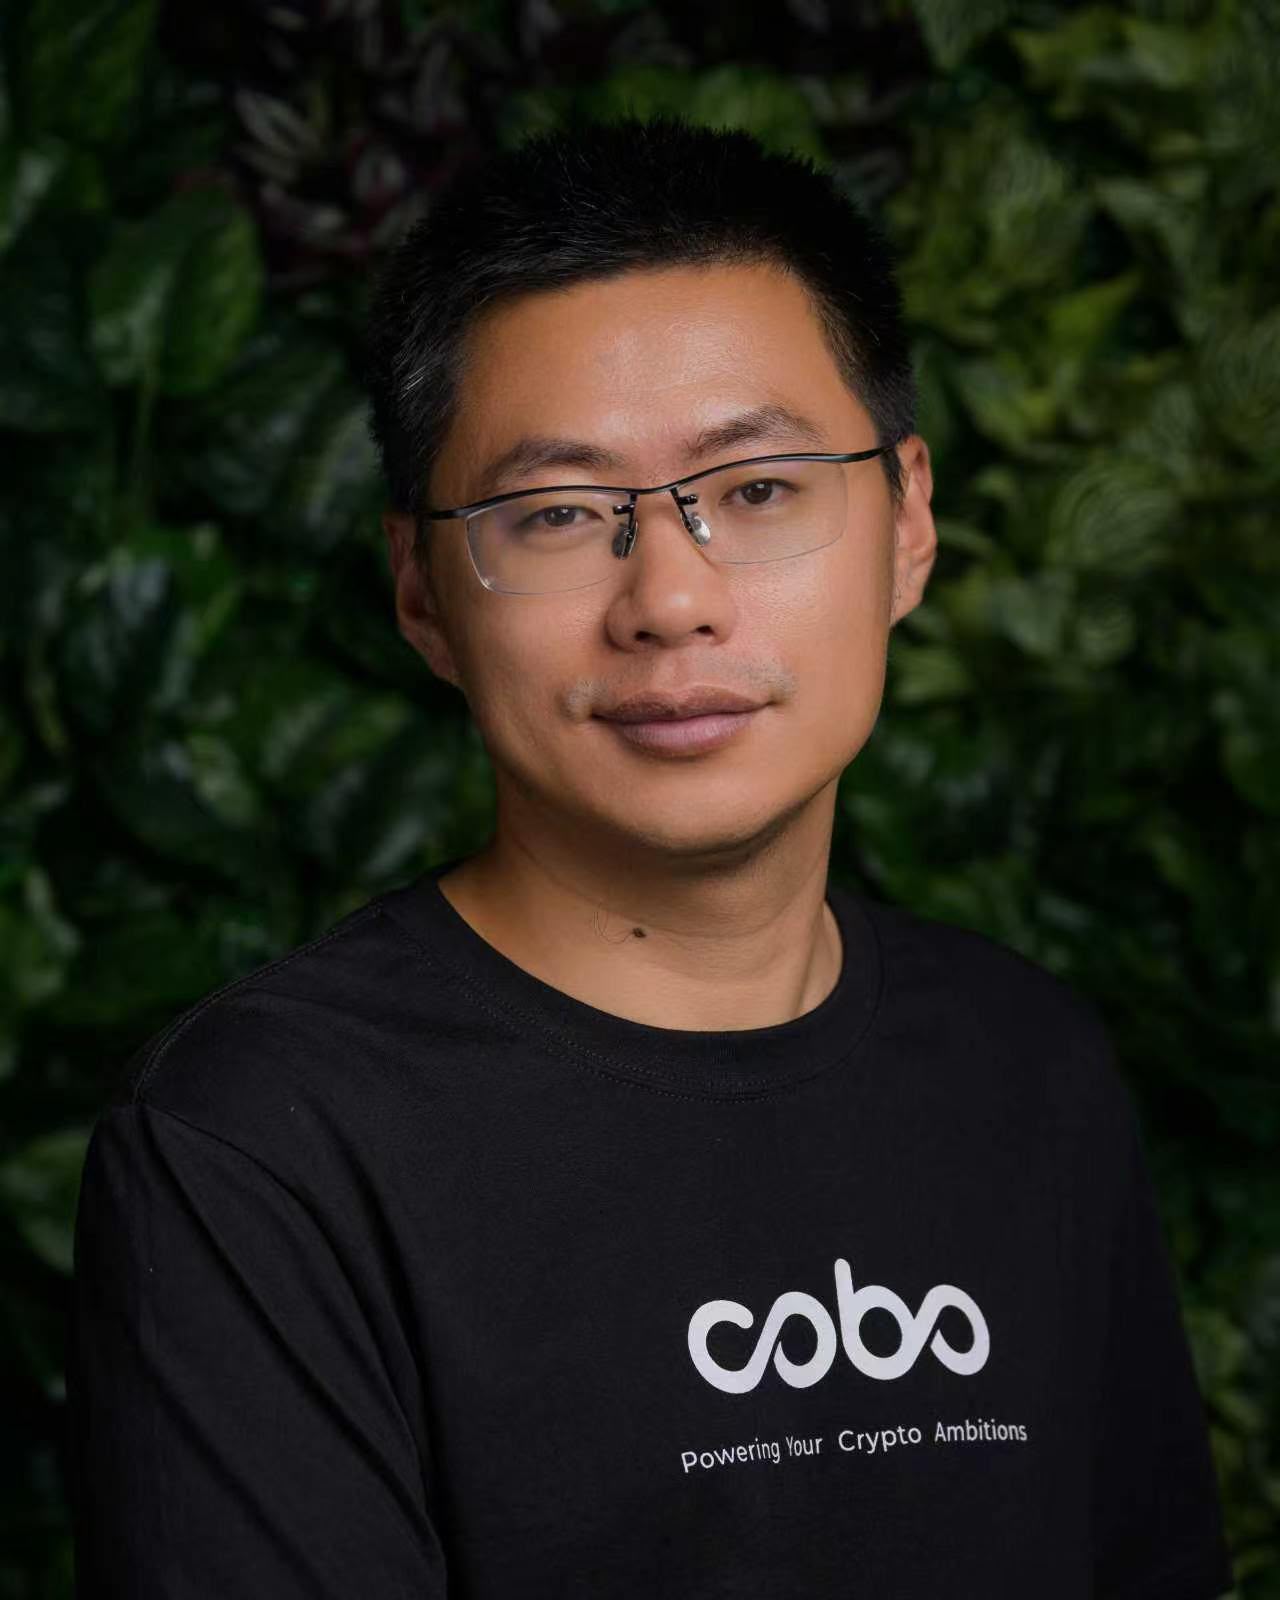
Discus Fish points to a longstanding challenge: blockchain can be difficult for everyday users to navigate, but AI agents may find it easier to interact with these networks.
“Blockchains have always been hard for ordinary people to use. AI agents may be better users: the chain is fully transparent and every record is traceable, which suits agents well.”
His outlook comes with a qualification. Both the agents and the networks they would use still need to develop.
“Agents aren’t capable enough yet, and chains are still adapting. But once agents truly run on-chain, the number of users and what’s possible will grow by an order of magnitude.”
Discus Fish says blockchain could reshape how financial assets are issued, traded and settled over the next five years. He also notes that institutional adoption has progressed faster than Cobo initially expected, with individual users no longer leading the shift. “Since 2017, we have believed blockchain will become part of the financial infrastructure of the future. We expected individual users to lead, but institutions moved faster.”
For Fish, the next stage involves a broader range of assets and financial clients.
“What gets redefined next is how assets are issued, traded, and settled. As traditional assets like US equities come on-chain, a much wider range of financial clients will follow.”
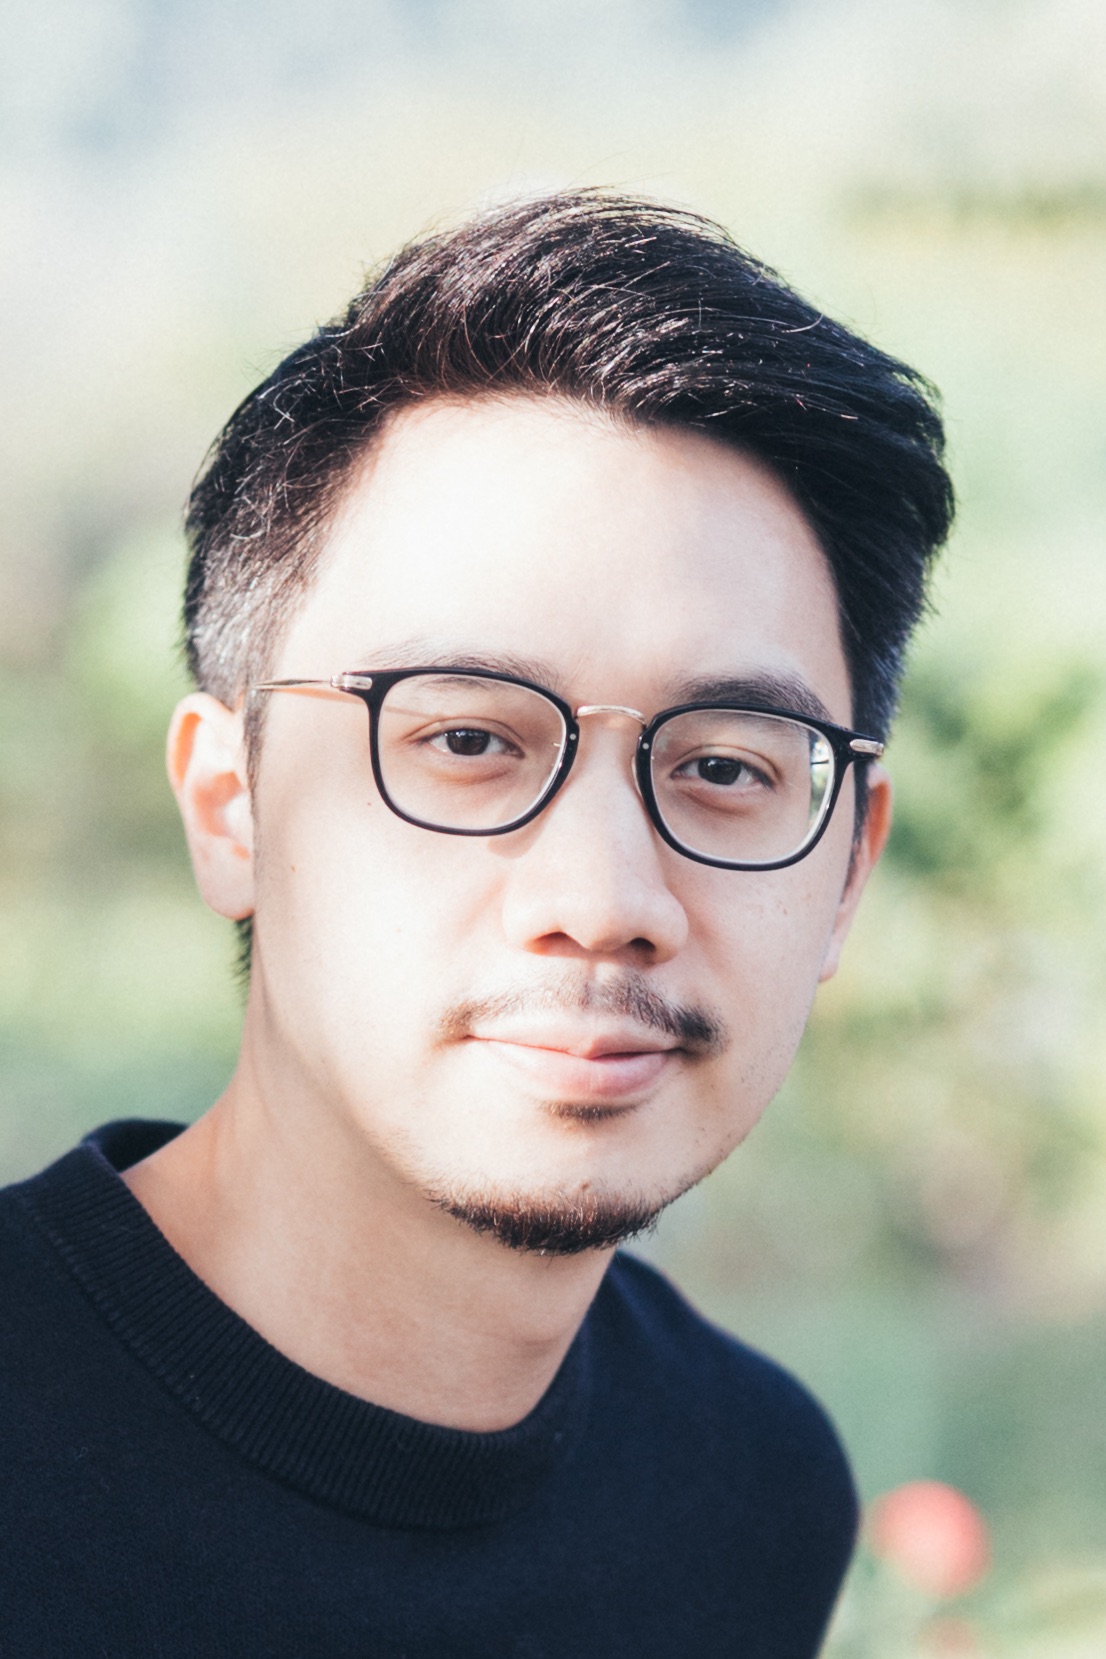
Samuel Tse, Head of Investment and Corporate Finance at Animoca Brands, focuses on investment opportunities across digital assets and agentic AI. He sees digital identity as essential to allowing AI agents to act on behalf of people while keeping transactions within the permissions they set.
He believes users should set clear rules for what an AI agent can do, allowing it to complete transactions without requiring approval for each one.
“Once agents can prove who they represent, hold digital assets, and move value under clear rules, the economy stops being click-by-click. You set the policy once—who, how much, for what—and the agent transacts inside it.”
He describes applications ranging from everyday payments and transfers to subscriptions, swaps and earning returns on idle funds. “That’s agentic transactions: payments, transfers, subscriptions, swaps, even chasing a better rate on idle cash. Identity is the trust layer. Assets and credentials are the spending authority—always accountable to the human who granted permission.”
In Tse’s account, the human remains the source of that authority. The agent acts within the permissions granted to it.
To illustrate how AI agents, digital identity and digital assets might work together, Tse offers a hypothetical Hong Kong parent's weekday.
“A Hong Kong parent’s weekday: top up the child’s Octopus, book a weekend football slot, translate a school notice for the helper, check weather before pickup, restock milk at the member price, and keep leftover budget earning until tomorrow.”
At present, he says, completing these tasks requires navigating services that often operate separately.
“Today that means many apps that don't talk to each other, and rails that struggle with micro payments.”
His proposed alternative brings the tasks together under instructions established by the user.
“With an agent, they set the rules once and let it decide what to do. Identity unlocks trust and member prices without oversharing. Digital assets fit the money—per-use fees, hard limits, yield until spend.”
For Tse, this combination could create opportunities across payments, merchants, identity providers and digital-asset platforms. He compares the potential scale of agentic commerce to an earlier change in how consumers accessed services.
“The iPhone in 2007 rewired how people buy and use services for 20 years. We are just at the beginning of a similar paradigm shift, with outcomes we can barely imagine.”
Discus Fish and Samuel Tse offer two perspectives on the emerging agentic economy, from the blockchain infrastructure enabling transactions to the digital identity and permissions that allow AI agents to act on people's behalf. At CVCF 2026, these ideas will become part of a wider conversation with the leaders building and investing in this evolving space.
Be part of the conversation. Join industry leaders, founders and investors at CVCF 2026 on 4–5 November and explore the technologies and opportunities shaping the next phase of business.
Exclusive for Ventureport readers: Use code cvcf26vp to access a Full Access Pass for HK$300, subject to confirmation by the organiser.
Keep Reading
Quantara AI launches a continuous platform designed to estimate the financial impact of cyber risk as companies move beyond periodic assessments
Updated
March 17, 2026 1:02 AM

A person tightrope walking between two cliffs. PHOTO: UNSPLASH
Cyber risk is increasingly treated as a financial issue. Boards want to know how much a cyber incident could cost the company, how it could affect earnings, and whether current security spending is justified.
Yet many organizations still measure cyber risk through periodic reviews. These assessments are often conducted once or twice a year, supported by consultants and spreadsheet models. By the time the report reaches senior leadership, the company’s systems may have changed and new threats may have emerged. The way risk is measured does not always match how quickly it evolves.
This gap is where Quantara AI is positioning its new platform. Quantara AI, a Boise-based cybersecurity startup, has introduced what it describes as the industry’s first persistent AI-powered cyber risk solution. The system is designed to run continuously rather than rely on occasional assessments.
The company’s core argument is straightforward: not every security weakness carries the same financial consequence. Instead of ranking issues only by technical severity, the platform analyzes active threats, identifies which company systems are exposed, and estimates how much money a successful attack could cost. It uses statistical models, including Value at Risk (VaR), to calculate potential losses. It also estimates how specific security improvements could reduce that projected loss.
The timing aligns with a broader market shift. International Data Corporation (IDC) projects that by 2028, 40% of enterprises will adopt AI-based cyber risk quantification platforms. These tools convert security data into financial estimates that can guide budgeting and investment decisions. The forecast reflects growing pressure on security leaders to present risk in terms that boards and regulators understand.
Traditional compliance and risk management systems often focus on meeting regulatory standards. Vulnerability management programs typically score weaknesses based on technical characteristics. Consultant-led risk studies provide detailed analysis, but they are usually performed at set intervals. In fast-changing threat environments, that model can leave decision-makers working with outdated information.
Quantara’s platform attempts to replace that periodic process with continuous measurement. It brings together threat data, internal system information and financial modeling in one system. The goal is to show, at any given time, which specific weaknesses could lead to the largest financial losses.
Cyber risk quantification as a concept is not new. What is changing is the expectation that these calculations be updated regularly and tied directly to financial decision-making. As cyber incidents carry clearer monetary consequences, companies are looking for ways to measure exposure with greater precision.
The broader question is whether enterprises will shift fully toward continuous, AI-driven risk analysis or continue relying on periodic external assessments. What is clear is that cybersecurity discussions are moving closer to financial reporting — and tools that estimate potential loss in dollar terms are becoming central to that shift.