
Discus Fish of Cobo and Samuel Tse of Animoca Brands discuss how AI agents, digital identity and blockchain could change the way money moves.
Updated
November 2, 2026 12:03 PM
The Agentic Economy Summit at CVCF 2026 explores how AI agents and digital assets could shape the future of business and finance. IMAGE: CYBERPORT
For an AI agent to manage money on someone’s behalf, it needs more than the ability to follow instructions. It must be able to establish whom it represents, access funds and transact within agreed limits.
These are among the questions informing the discussion of AI and digital assets at Cyberport Venture Capital Forum (CVCF) 2026. Ahead of the forum, Discus Fish, CEO and Co-founder of Cobo, and Samuel Tse, Head of Investment and Corporate Finance at Animoca Brands, shared their views on how this convergence could develop—and where they see opportunities for businesses.
Discus Fish points to a longstanding challenge: blockchain can be difficult for everyday users to navigate, but AI agents may find it easier to interact with these networks.
“Blockchains have always been hard for ordinary people to use. AI agents may be better users: the chain is fully transparent and every record is traceable, which suits agents well.”
His outlook comes with a qualification. Both the agents and the networks they would use still need to develop.
“Agents aren’t capable enough yet, and chains are still adapting. But once agents truly run on-chain, the number of users and what’s possible will grow by an order of magnitude.”
Discus Fish says blockchain could reshape how financial assets are issued, traded and settled over the next five years. He also notes that institutional adoption has progressed faster than Cobo initially expected, with individual users no longer leading the shift. “Since 2017, we have believed blockchain will become part of the financial infrastructure of the future. We expected individual users to lead, but institutions moved faster.”
For Fish, the next stage involves a broader range of assets and financial clients.
“What gets redefined next is how assets are issued, traded, and settled. As traditional assets like US equities come on-chain, a much wider range of financial clients will follow.”
Samuel Tse, Head of Investment and Corporate Finance at Animoca Brands, focuses on investment opportunities across digital assets and agentic AI. He sees digital identity as essential to allowing AI agents to act on behalf of people while keeping transactions within the permissions they set.
He believes users should set clear rules for what an AI agent can do, allowing it to complete transactions without requiring approval for each one.
“Once agents can prove who they represent, hold digital assets, and move value under clear rules, the economy stops being click-by-click. You set the policy once—who, how much, for what—and the agent transacts inside it.”
He describes applications ranging from everyday payments and transfers to subscriptions, swaps and earning returns on idle funds. “That’s agentic transactions: payments, transfers, subscriptions, swaps, even chasing a better rate on idle cash. Identity is the trust layer. Assets and credentials are the spending authority—always accountable to the human who granted permission.”
In Tse’s account, the human remains the source of that authority. The agent acts within the permissions granted to it.
To illustrate how AI agents, digital identity and digital assets might work together, Tse offers a hypothetical Hong Kong parent's weekday.
“A Hong Kong parent’s weekday: top up the child’s Octopus, book a weekend football slot, translate a school notice for the helper, check weather before pickup, restock milk at the member price, and keep leftover budget earning until tomorrow.”
At present, he says, completing these tasks requires navigating services that often operate separately.
“Today that means many apps that don't talk to each other, and rails that struggle with micro payments.”
His proposed alternative brings the tasks together under instructions established by the user.
“With an agent, they set the rules once and let it decide what to do. Identity unlocks trust and member prices without oversharing. Digital assets fit the money—per-use fees, hard limits, yield until spend.”
For Tse, this combination could create opportunities across payments, merchants, identity providers and digital-asset platforms. He compares the potential scale of agentic commerce to an earlier change in how consumers accessed services.
“The iPhone in 2007 rewired how people buy and use services for 20 years. We are just at the beginning of a similar paradigm shift, with outcomes we can barely imagine.”
Discus Fish and Samuel Tse offer two perspectives on the emerging agentic economy, from the blockchain infrastructure enabling transactions to the digital identity and permissions that allow AI agents to act on people's behalf. At CVCF 2026, these ideas will become part of a wider conversation with the leaders building and investing in this evolving space.
Be part of the conversation. Join industry leaders, founders and investors at CVCF 2026 on 4–5 November and explore the technologies and opportunities shaping the next phase of business.
Exclusive for Ventureport readers: Use code cvcf26vp to access a Full Access Pass for HK$300, subject to confirmation by the organiser.
Keep Reading
Can innovation truly deliver affordable housing to those who need it most?
Updated
January 8, 2026 6:35 PM
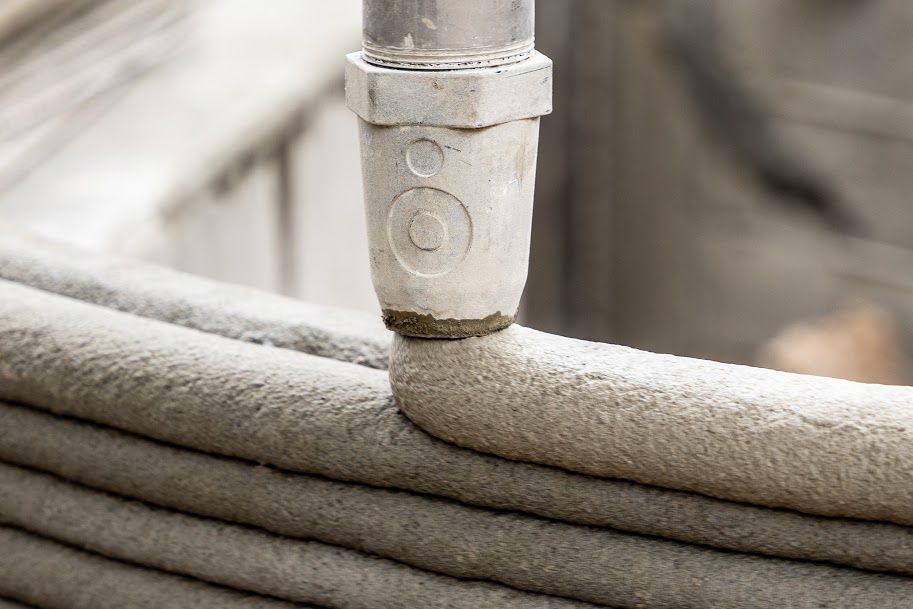
Close up of a 3D printer nozzle pouring concrete. PHOTO: ICON
The affordable housing crisis has become one of the most pressing challenges of our time. Across the globe, millions of people are struggling to secure a roof over their heads. In cities like San Francisco, housing prices are so high that even middle-income families find themselves shut out of the market.
The root of this crisis lies in a persistent imbalance: the supply of housing has failed to keep pace with growing demand. Factors such as high construction costs, bureaucratic hurdles, and limited available land in urban areas have made it increasingly difficult to build enough homes quickly and affordably. The result is a market where housing remains inaccessible to millions, even as the need becomes more urgent.
Technology is now stepping in to address these challenges in ways that were unimaginable just a decade ago. From streamlining construction processes to introducing new financing models and data-driven tools, tech innovations are rethinking how homes are built, financed, and accessed. But while these advancements offer hope, they also raise important questions: can they truly address the root causes of the housing crisis, or are they simply patching up a fractured system?
The housing crisis begins with supply shortage: we simply aren’t building enough homes. Traditional construction methods are expensive, slow, and reliant on labor that is increasingly hard to find. This is where technology is making its most significant impact. Startups likeICON and Veev are leading the charge, using cutting-edge solutions to make housing more efficient and affordable.
ICON, for instance, uses 3D printing to build homes faster and at a lower cost. By printing the structure of a house directly on-site, ICON reduces waste, labor requirements, and construction time. Entire neighborhoods of 3D-printed homes are already being built, showcasing how this technology can scale.
Veev, on the other hand, focuses on prefabricated construction. By manufacturing high-quality components like walls and steel frames in a controlled factory environment, Veev eliminates inefficiencies associated with on-site building. These components are then assembled on location, drastically reducing construction time and costs. This approach mirrors the principles of mass production seen in industries like automotive manufacturing, where efficiency and scalability are key.
While building more homes is essential, access to housing often depend son financing. For many people, especially those with low or irregular incomes, the traditional mortgage system presents insurmountable barriers. Fintech innovations are stepping in to make housing financing more inclusive and flexible.
Access to affordable housing often hinges on financing, and innovative financial technology (fintech) solutions are beginning to change the landscape. Some platforms are offering new ways for individuals to transition from renting to owning, while others are introducing shared equity models that reduce the traditional barriers of large down payments and strict credit requirements. For example, companies like Point use shared-equity financing, where homeowners receive funds in exchange for a percentage of their home’s future value instead of taking on traditional debt. Meanwhile, startups are building tools that automate and simplify and revolutionizing the mortgage process, making it easier for underserved populations to access loans tailored to their needs.
Blockchain technology is also changing the game. By digitizing land titles and creating secure records of financial transactions, blockchain reduces the complexity and difficulty of accessing credit, especially for those with limited traditional credit. This is particularly impactful in regions where informal economies dominate and traditional proof of income is scarce. These tools create a pathway to homeownership for individuals who would otherwise be excluded from the system.
Beyond building and financing, technology is transforming how we understand and address housing needs. Artificial intelligence (AI) is revolutionizing risk assessment in the mortgage industry by analyzing a broader range of financial behaviors, such as rent and utility payments, to provide a more inclusive picture of creditworthiness.
At the same time, AI and big data are helping policymakers and developers make smarter decisions about where and how to build. By analyzing population trends, commuting patterns, and infrastructure needs, these tools ensure that new housing developments are built in the right places, reducing wasteful construction and improving urban planning.
For example, startups are using 3D scanning and machine learning to map informal settlements and identify buildings at risk of collapse. These insights not only improve safety but also guide investment toward areas where housing is most desperately needed.
The housing crisis is one of the most complex challenges of our time, and technology alone cannot solve it. But it can provide powerful tools to address specific pain points, from streamlining construction to expanding access to financing. Startups like ICON, Veev, and Landis are proving that innovation can lower costs, improve efficiency, and make housing more inclusive.
However, the ultimate solution lies in a combination of technology, policy reform, and community engagement. Governments must work alongside tech innovators to create urban environments that prioritize affordability, sustainability, and accessibility.
The future of housing isn’t just about building more homes; it’s about building smarter, greener, and fairer cities where everyone has a place to call home. By integrating cutting-edge technologies with forward-thinking policies, we can move closer to a world where affordable housing is not an aspiration but a reality.
The question is no longer whether technology can solve the housing crisis—it’s how we will use it wisely to create lasting change.